This is paragraph text. Click it or hit the Manage Text button to change the font, color, size, format, and more. To set up site-wide paragraph and title styles, go to Site Theme.
September 2026 Newsletter
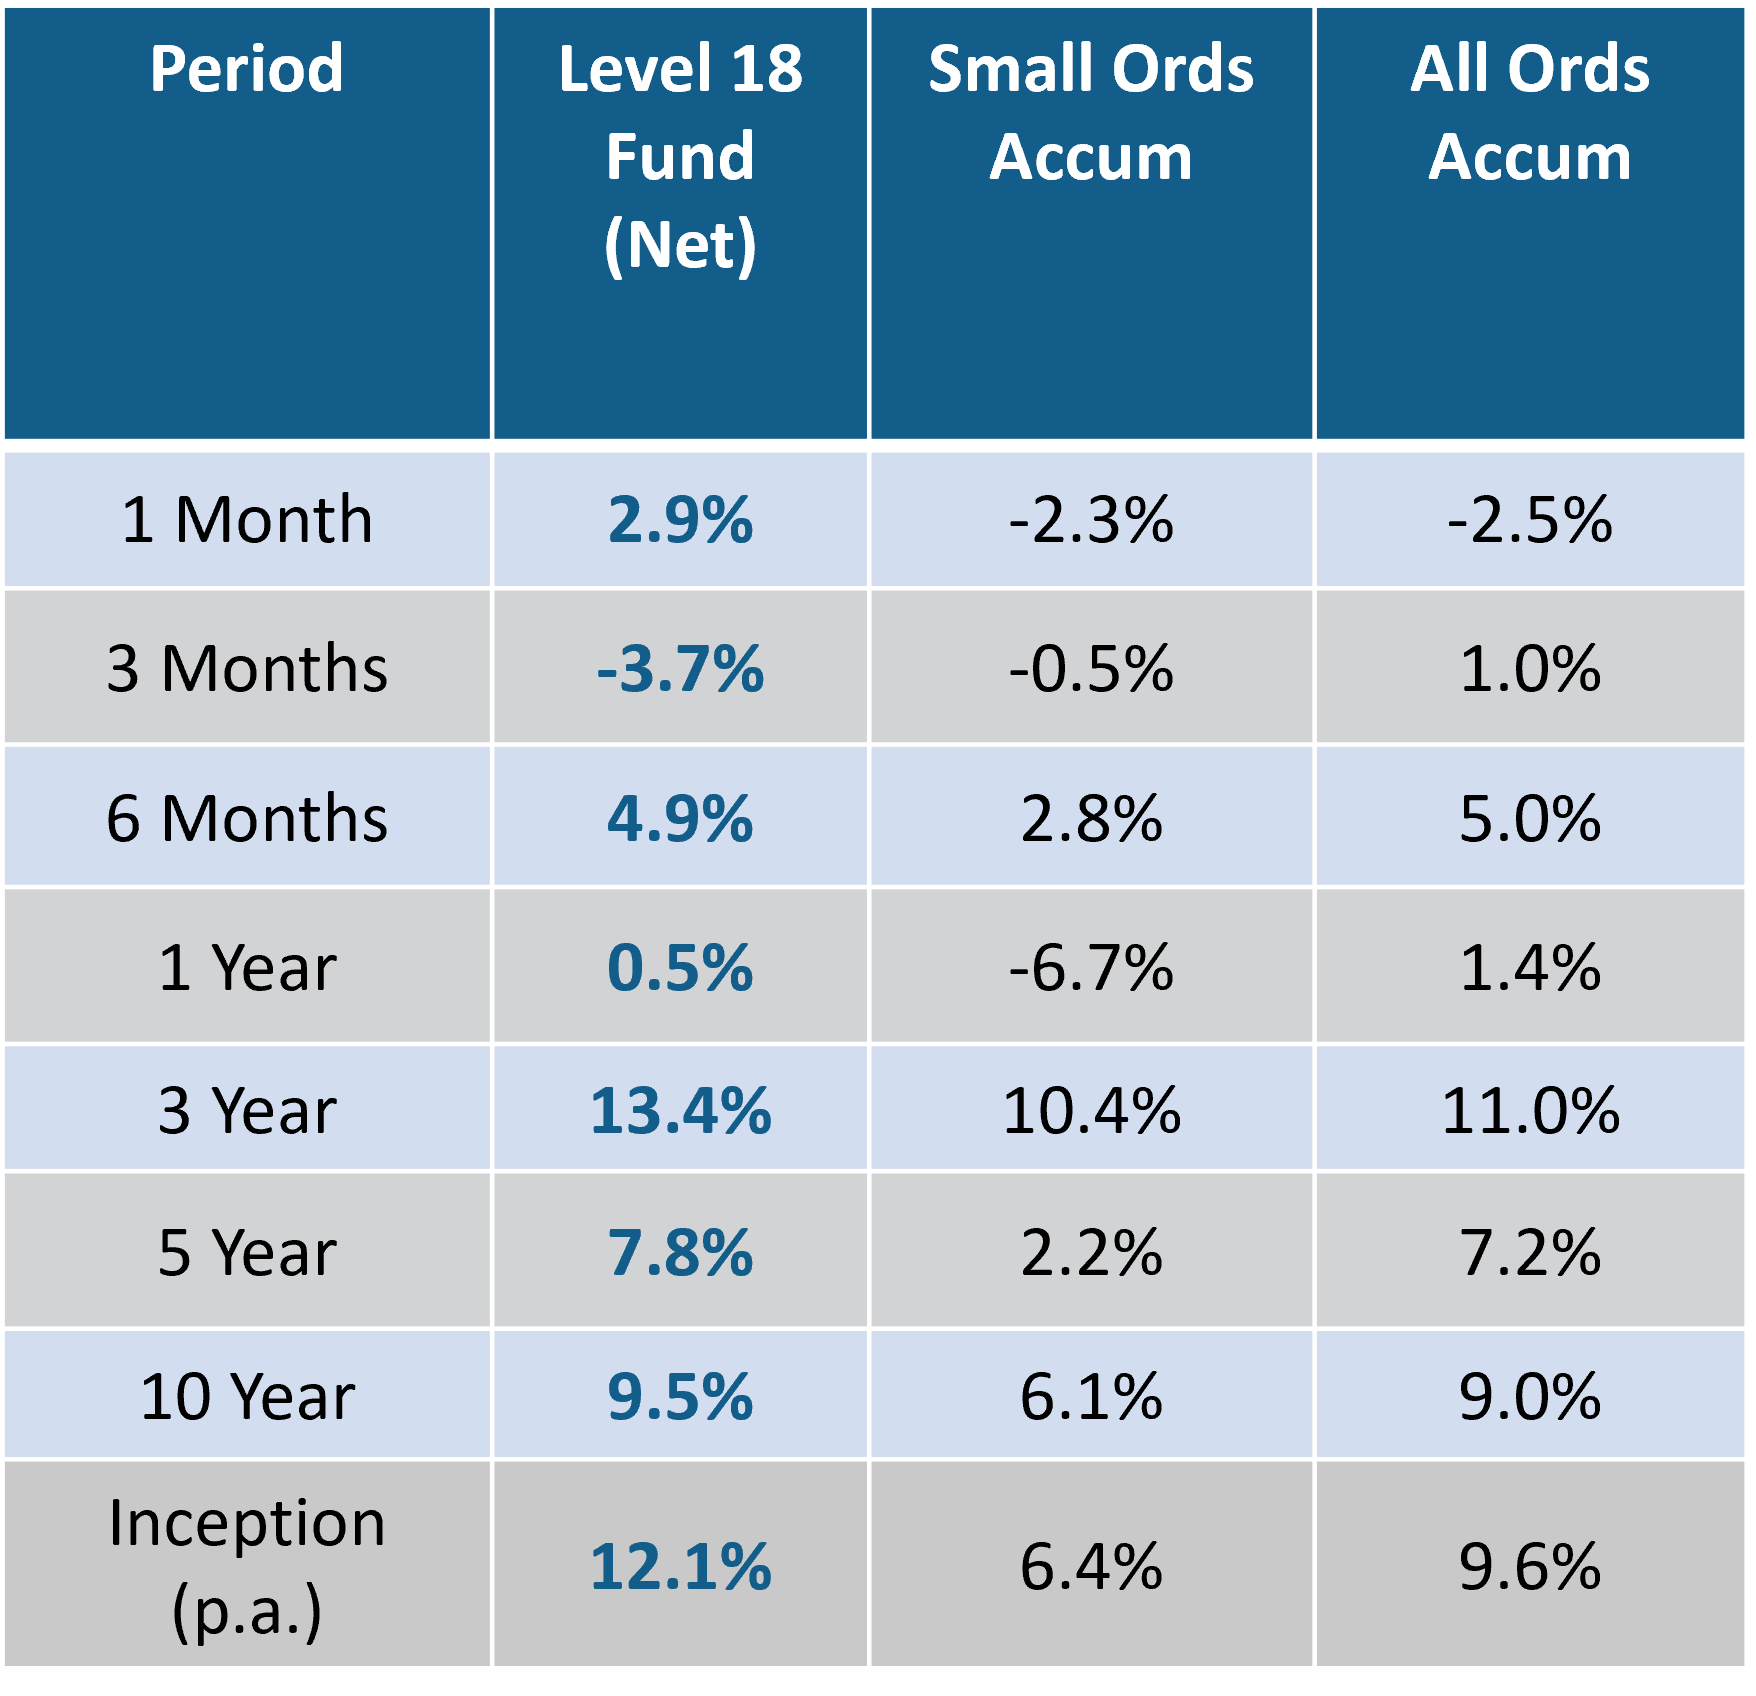
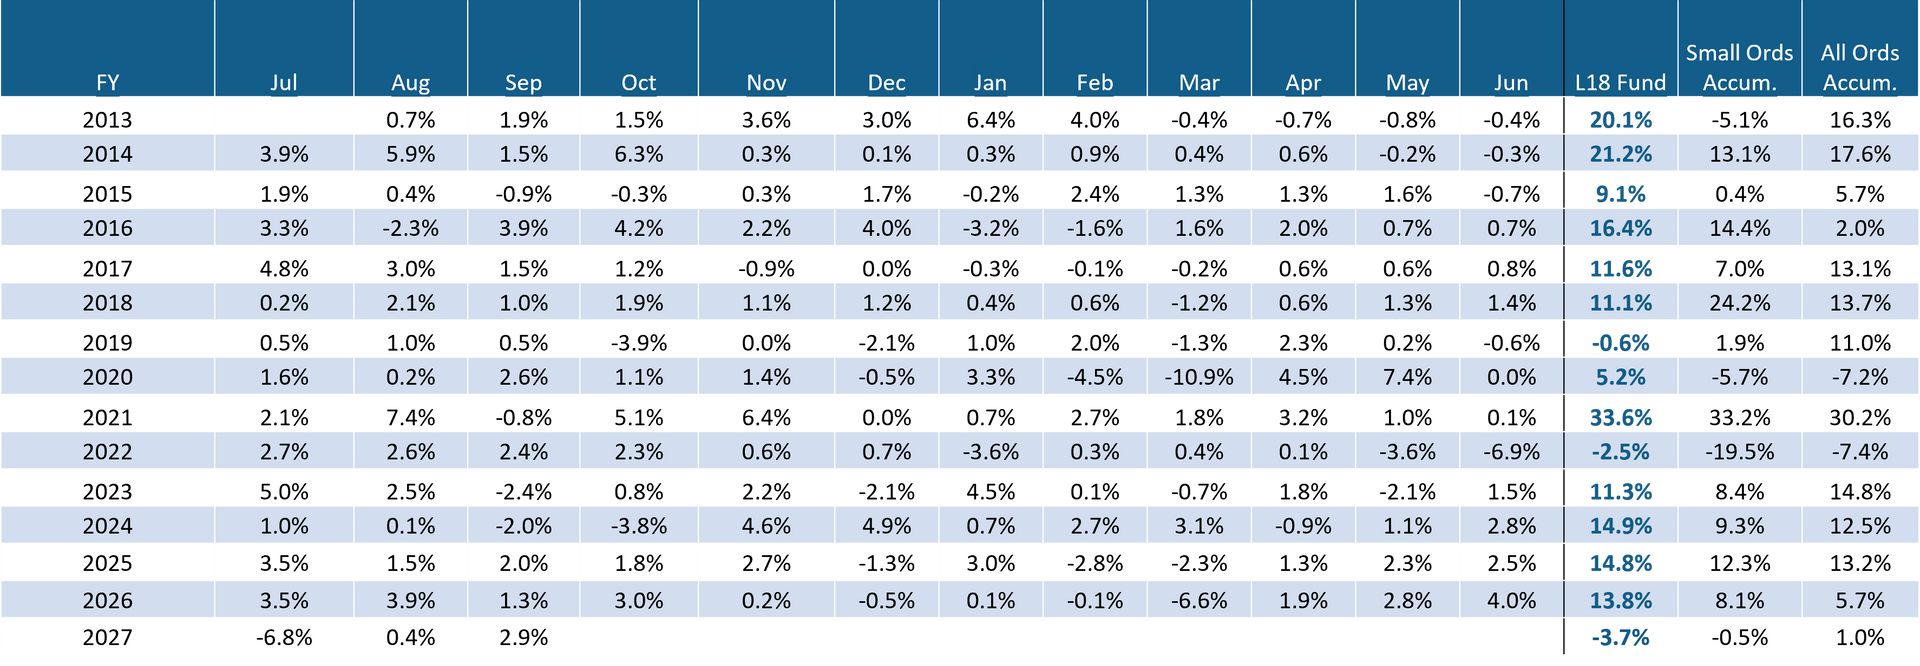
The Level 18 Fund increased by 2.9 per cent net of fees for the month.
Commentary
The Level 18 Fund increased by +2.9 per cent net of fees for the month.
In Australia, the All Ordinaries Accumulation Index decreased by -2.5 per cent during the month due to a combination of modest forecast earnings growth, elevated inflation, interest rate increases and lower exposure to AI stocks.
US equities outperformed the local market in September. Superior forecast earnings growth and a structurally larger exposure to AI investment thematics drove performance. US investors rotated into semiconductors, software and AI infrastructure stocks during the month. The S&P 500 finished the month down -0.5 per cent and the Nasdaq Composite Index up +1.9 per cent.
The S&P/ASX Small Ordinaries Accumulation Index slightly outperformed large caps for the month, down -2.3 per cent. During September, small cap industrials and small cap resources were down -2.1 per cent and -4.8 per cent respectively. In contrast to the strong +10 per cent move in the gold price in August, it declined by -5.8 per cent in September.
In Australia, Healthcare was the best performing sector. CSL continued to lift the index with a rise of +37 per cent since the FY26 result in August. Energy was the only other sector with a positive return in the month (+0.5 per cent). Tech was the worst sector, down -9.8 per cent. Xero (XRO) and Wisetech Global (WTC) were down -33.5 and -19.8 per cent respectively.
Rising bond yields dominated global macro headlines during September. The rapid rise in long-term bond yields created valuation headwinds for equities. US 10-year Treasury yields climbed above 5 per cent, reaching their highest levels since 2007. In Australia, 10-year bond yields climbed to a peak of 5.44 per cent towards the end of the month. The resulting increase in discount rates created valuation pressures for equities, particularly for the rate-sensitive sectors such as property, utilities, consumer discretionary and financial sectors. Interest rate yields increased due primarily to inflation concerns as higher energy costs are forecast to flow through to the broader economy via transportation, manufacturing and consumer prices.
In Australia the RBA increased interest rates for the fourth time this year to 4.6 per cent. The highest level in 15 years. Post the RBA board meeting, the bank indicated that inflation pressures were proving more persistent than desired and that returning inflation to target remained the Board's highest priority. Importantly, the RBA did not signal that rates had peaked. Instead, it left the door open to additional tightening if inflation and demand remained stronger than expected. The next RBA meeting is scheduled for early November 2026.
In the US, The Federal Reserve increased rates by 0.25 per cent to a range of 3.75 to 4.00 per cent. The move was the first interest rate hike since July 2023. Federal Reserve Chair, Kevin Warsh, said inflation had been "too high and for too long” and the rate increase would support a faster return to its 2.0 per cent inflation goal. Further, the Fed also noted that US economic activity was expanding at a solid pace, domestic spending remained resilient, productivity growth was strong, and business investment remained robust. The next Federal Reserve meeting is in late October 2026.
Finding growth in the Australian economy remains challenging. However, there are pockets of growth particularly within the mining services, engineering and construction, electrification and data-centre infrastructure sectors. During the month several portfolio positions delivered earnings upgrades that were ahead of expectations.
Codan (CDA) was a standout. The company posted an earnings upgrade showing a significant acceleration in the Communication business. The unmanned drone segment was the key contributor, driving strong revenue growth and significant operating leverage. As a result, Codan now expects to achieve Group NPAT for H1 FY27 of not less than $160M, representing over 100 per cent growth on the $71.2M in the previous corresponding period and nearly matching the full year profit of $175.2M in FY26.
Megaport (MP1) also delivered an additional contract win and earnings upgrade during the month. Specifically, MP1 announced three new strategic take-or-pay style compute contracts with a combined Total Contract Value of A$979M. Revenue and EBITDA guidance has been increased by approximately +13 per cent and +25 per cent respectively. The new strategic contracts are the key contributors to the improved outlook for guidance and operating margins.
During the month we added several new exposures to the portfolio including QBE Insurance (QBE), NRW Holdings (NWH), Monadelphous (MND), Bapcor (BAP) and Adrad Holdings (AHL).
The Fund continues to navigate capital markets through a seasonally weak period. The portfolio remains focused on capital preservation while seeking to optimise returns amid persistent inflationary pressures, elevated bond yields and heightened earnings risk. Liquidity and earnings visibility remain key portfolio construction considerations. Reflecting the current market environment, the Fund has maintained an above-average cash weighting of approximately 25 per cent.
Positive contributors to the Fund’s performance in September include technology development group Codan (CDA), audio-visual & electrical contractor SKS Technologies (SKS), equipment financing and broking business COG Financial Services (COG) and power distribution and industrial communications group IPD Group (IPG).
Online vehicle marketplace business
CAR Group (CAR), healthcare imaging and radiology software business
Pro Medicus (PME)
and
telecommunication and internet service provider
Superloop
(SLC)
made negative contributions to performance in the month.
Please contact Michael Carmody (mcarmody@centennialfunds.com.au or +61 414 952 985) if you would like any additional information regarding the fund.
The Level 18 Fund Information Memorandum (IM) is available on the Centennial Asset Management website. The following link (https://www.centennialfunds.com.au/) provides access to the IM.
The Centennial Team
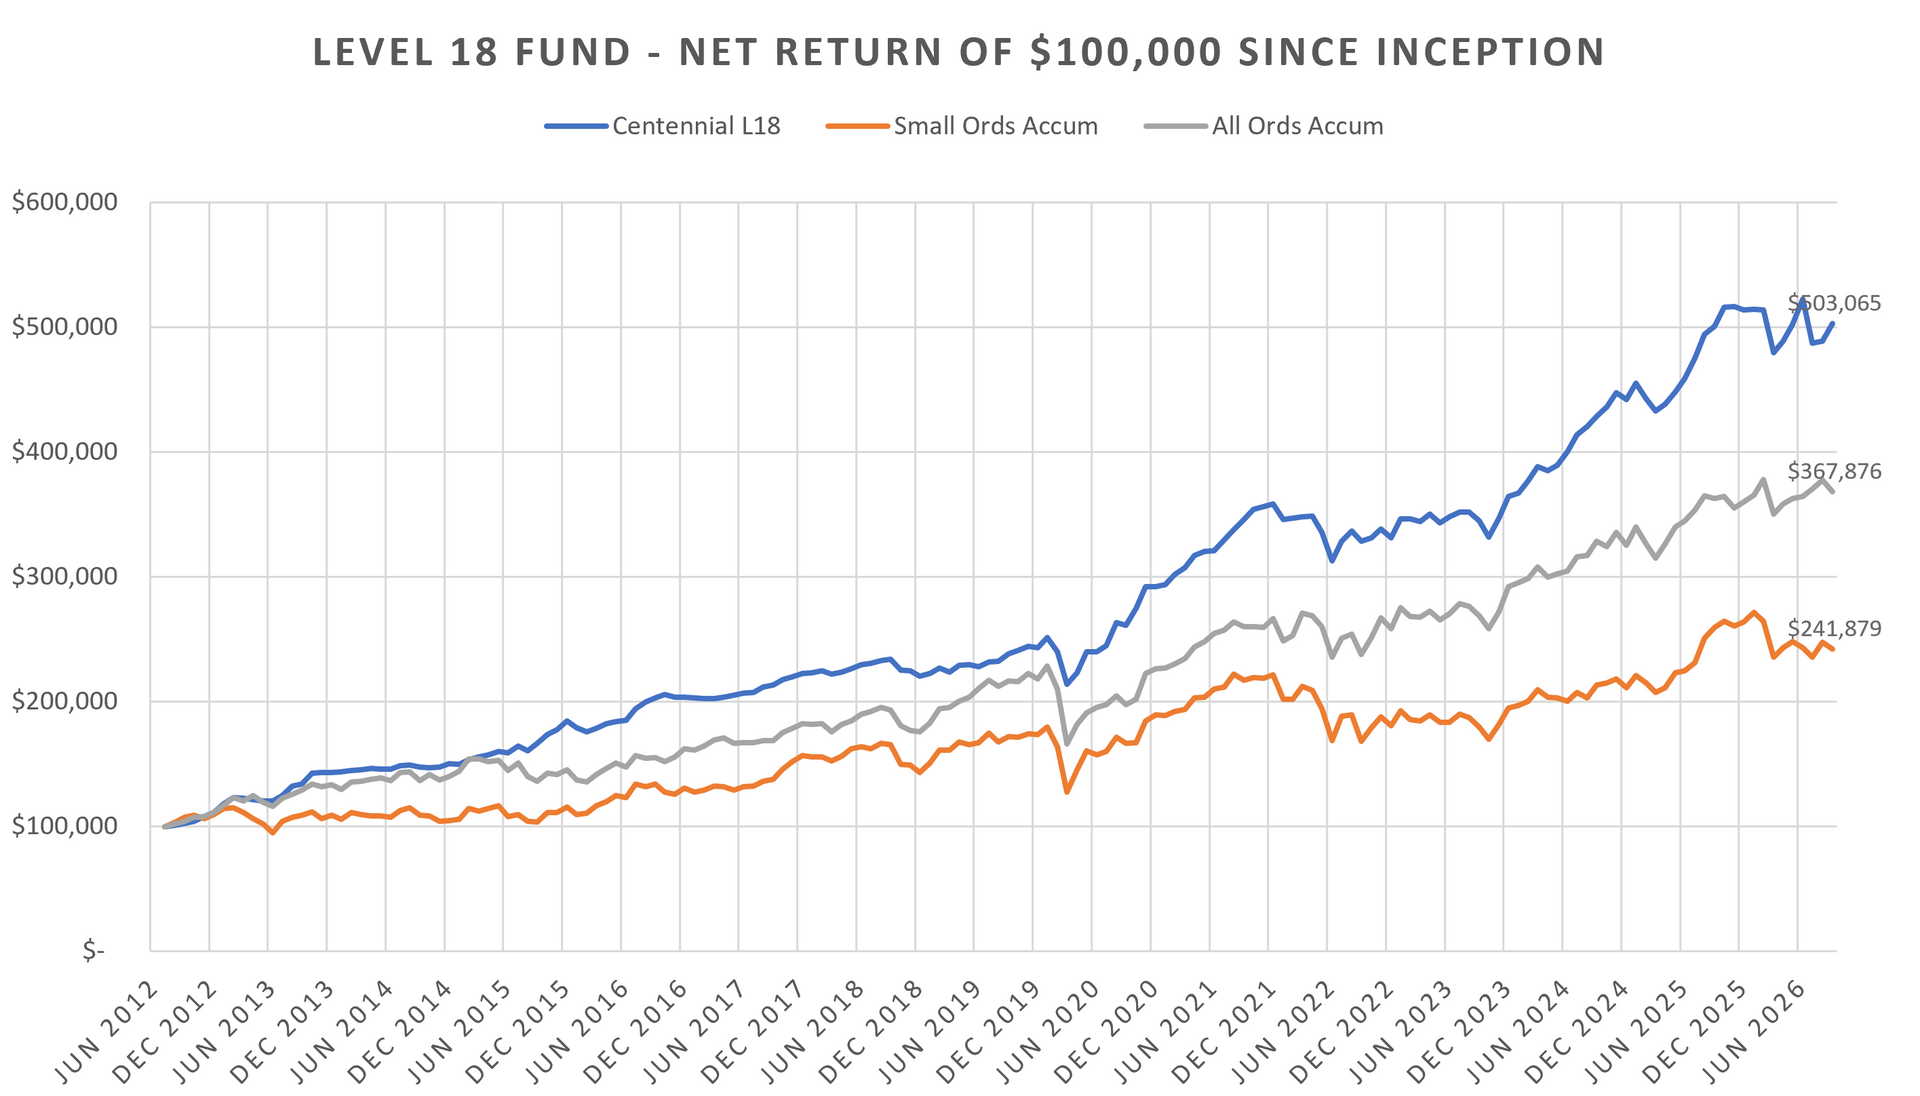
Monthly Net Returns Since Inception
About Centennial Asset Management
Centennial Asset Management is an independent Australian asset management business, and the manager of the Level 18 Fund, an index unaware fund, with asset allocation flexibility and a concentration of small capitalised companies. Further information on Centennial is available on our website - www.centennialfunds.com.au
Disclaimer
Strictly confidential: This report has been prepared by Centennial Asset Management ACN 605 827 745 & AFSL No. 515887 for Wholesale Clients only as an indicative record of the performance of an investment in the Level 18 Fund. No recommendation is made or advice given in respect of any entity in which the Level 18 Fund has, is or may in the future be, invested. The contents of this report are confidential, and the client may only disclose such contents to its officers, employees or advisers on a need to know basis, or with the prior written consent of Centennial Asset Management. Centennial Asset Management does not guarantee the performance of the Level 18 Fund or the return of any investor's capital in the Level 18 Fund. This investment report contains historical information, and does not imply any indication of future performance, recommendation or advice. Past performance is not a reliable indicator of future performance. Any investment needs to be made in accordance with and after reading any relevant offer document. This material has been prepared based on information believed to be accurate at the time of publication. Assumptions and estimates may have been made which may prove not to be accurate. Centennial Asset Management accepts no responsibility to correct any such inaccuracy. Subsequent changes in circumstances may occur at any time and may impact the accuracy of the information. To the full extent permitted by law, none of Centennial Asset Management, or any related body corporate or any officer or employee of any of them makes any warranty as to the accuracy or completeness of the information in this report and disclaims all liability that may arise due to any information contained in this newsletter being inaccurate, unreliable or incomplete. *Prior to launch of the Level 18 Fund on 1 September 2014, Centennial Asset Management had established a separately managed account (“SMA”) and performance prior to 1 September 2014 is illustrated on a gross pro-forma basis, that invests with the same mandate as the Level 18 Fund and is included in the tables above, for comparative purposes only. The returns assume reinvestment of distributions.